
In brief
Apply through the UAE Federal Tax Authority for the certificate appropriate to your purpose and period. A treaty-purpose application and a domestic-purpose application have different requirements.
Source for this answer: UAE Federal Tax Authority: Issuance of tax residency certificates
What can change the answer: A certificate supports a residence claim; it does not establish every condition for an Indian treaty benefit. Have the particular income and tax period assessed.
More context
A sample tax domicile certificate is not evidence of your residence. The UAE Federal Tax Authority offers treaty-purpose and other certificates, with evidence appropriate to the request. Domestic UAE residence criteria should not be substituted for a particular treaty test. Current Indian Form 41 provides treaty particulars under the 2025 Act; it does not itself grant exemption.
Keep citizenship, tax residence and FEMA residence separate
These labels answer different questions. Your nationality or OCI card does not alone determine the year’s Indian tax treatment. Establish the relevant year, travel history, income sources and exceptions.
Your next steps
0 of 5 steps complete · Next: Confirm the certificate you need
Confirm the certificate you need
Next stepIdentify the treaty country, relevant income period and whether the request is for DTA purposes.
Collect the FTA’s current evidence
Use the official service checklist for identity, entry/exit, residence and supporting income information applicable to your circumstances.
Apply through the official FTA route
Start from the FTA service page and use its EmaraTax/TRC service links. Keep private documents within the official application process.
Submit the required Indian tax information
For the 2025 Act route, use the e-filing portal’s income-tax forms section, select Form 41 and the relevant tax year, then complete its particulars, residence and verification panels.
Retain and reconcile the records
Keep the issued certificate, covered dates and filing acknowledgement. Confirm that they support the actual treaty claim and relevant transaction period.
Suggested preparation sequence. Your authority may require a different order. Progress stays on this device.
What to have ready
0 of 4 preparedKeep documents in your own secure records. Tick what you have; nothing is uploaded.
Check the certificate, period and proposed treaty claim together
Define the request
Write down the income or transaction, its date, the country involved and the certificate period requested by your adviser. Ask whether the application is for treaty purposes.
Prepare the evidence
Use the current FTA service checklist. Keep travel records, identity and residence evidence ready in your secure records; exact requirements depend on the application.
Before relying on the certificate
Ask your Indian adviser to explain how the certificate and applicable filing requirements support the particular claim. Retain the application, issued certificate and advice together. A certificate does not decide every tax question.
Practical checklist added 2026-09-23. This is an editorial addition, not a fresh review of every legal statement in the guide.
Model the decision with your own figures
Prepare the dates, currencies, costs and amounts you know. Keep tax eligibility, provider access and uncertain assumptions on your adviser’s question list. The calculators show those assumptions explicitly.
For a return to India, add education, parents’ support, healthcare, partner income and locked funds to the household timeline. Bring supporting-tool figures into it only after reviewing timing, currency and overlap.
Illustrative situation
A certificate covers one period but an investment disposal occurs in another. Ask the adviser whether further residence evidence or a different certificate period is needed.
A fictional preparation example, not a determination of eligibility, tax or legal rights.
Recognise the official form
Preview before you visit the official portal. Do not enter or upload personal information here.
 Enlarge preview ↗
Official online screen example
Form 41 · Treaty information
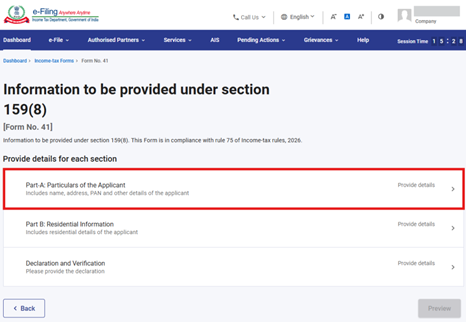
The department’s manual shows the online form for prescribed information supporting a non-resident’s treaty-relief claim under section 159 and Rule 75.
What you will see on the form
Part A: applicant particulars · Part B: residential information · Declaration and verification
This is a screenshot from the official manual, not a blank paper form or proof of eligibility. Confirm the tax year and applicable Act with your CA. Filing is online through the official e-Filing portal.
Income Tax Department · Source checked 5 September 2026
Questions to take to an adviser
- Does this certificate meet the India–UAE treaty residence test?
- Which tax year and form framework apply to my claim?
- Does the certificate period cover the transaction and required particulars?
Who can help
The UAE FTA for the certificate process and a CA for the Indian treaty claim and applicable year.
Check an adviser before paying or signingClaims, exceptions and the supporting evidence
Check what you may have heard
Source review: 5 September 2026 · Rules may change after this date.
Form 41 is used to furnish treaty information.
The Income Tax Department publishes a current Form 41 manual under the 2025 Act, Section 159 and Rule 75. Select the relevant tax year. Older Form 10F references concern the earlier framework; neither a form nor a TRC alone guarantees exemption.
The displayed tax domicile certificate proves current UAE treaty residence.
The image contains sample names and reference placeholders and an old stated period. Its authenticity cannot be established from the picture. Apply through the UAE Federal Tax Authority and check the certificate purpose and covered period.
Sources & review limits
Published by NRIdisha. Prepared with AI assistance. No individual author or qualified professional reviewer is credited for this guide.
Editorial change 2026-09-23: clearer title, direct opening answer, practical preparation checklist, illustrative situation and related guides. Sources beside factual opening answers identify the supporting material; practical suggestions are labelled separately. Earlier source-check dates remain unchanged.
Official sources support the statements they address. They do not certify this guide or your eligibility. Open the source and check current amendments before acting.
Income Tax Department (opens in a new tab) · Reserve Bank of India (opens in a new tab) · National Portal of India (opens in a new tab)
Official application route, evidence and distinction between treaty-purpose and other certificates.
Notification 282/2007: UAE individual treaty residence and the amended capital-gains article. Read with the treaty and subsequent applicable instruments.
Current 2025 Act form for non-resident treaty particulars under Section 159 and Rule 75; choose the applicable tax year.
Effective from 1 April 2026. Sections 70, 92 and 99 address transfers, gifts and clubbing; sections 82 and 85 address specified reinvestment relief.
Keep this page’s title, the exact statement and the official source. Email them to support@nridisha.com. Do not include personal documents.