
In brief
An Indian passport, UAE visa or TRC does not by itself settle a capital-gains claim. The India–UAE protocol contains a residual capital-gains provision, but applying it to fund units requires legal interpretation and all eligibility conditions. Buying units before moving abroad neither proves nor automatically defeats a claim. No country-wide zero-tax recommendation is made here.
Start with Income Tax Department: India–UAE treaty: 2007 protocol (opens in a new tab)
Keep citizenship, tax residence and FEMA residence separate
These labels answer different questions. Your nationality or OCI card does not alone determine the year’s Indian tax treatment. Establish the relevant year, travel history, income sources and exceptions.
Your next steps
0 of 5 steps complete · Next: Establish residence for the relevant period
Establish residence for the relevant period
Next stepRecord the sale date and your presence and residence facts. The UAE individual treaty test in the protocol refers to 183 days in the calendar year concerned.
Identify exactly what is sold
Provide the scheme documents, unit type, acquisition history and whether the activity is investment or business.
Read the complete treaty position
Ask the CA to identify the relevant article, protocols, applicable MLI changes, anti-abuse conditions and any supported case law.
Prepare the current certificate and form
Obtain an appropriate treaty-purpose TRC and follow the period-specific Indian form requirements. Form 41 is available under the 2025 Act.
Agree reporting and withholding treatment
Ask the fund and CA how the position will be handled in withholding, the Indian return and any refund, then check residence-country reporting.
Suggested preparation sequence. Your authority may require a different order. Progress stays on this device.
What to have ready
0 of 4 preparedKeep documents in your own secure records. Tick what you have; nothing is uploaded.
Model the decision with your own figures
Prepare the dates, currencies, costs and amounts you know. Keep tax eligibility, provider access and uncertain assumptions on your adviser’s question list. The calculators show those assumptions explicitly.
For a return to India, add education, parents’ support, healthcare, partner income and locked funds to the household timeline. Bring supporting-tool figures into it only after reviewing timing, currency and overlap.
Recognise the official form
Preview before you visit the official portal. Do not enter or upload personal information here.
 Enlarge preview ↗
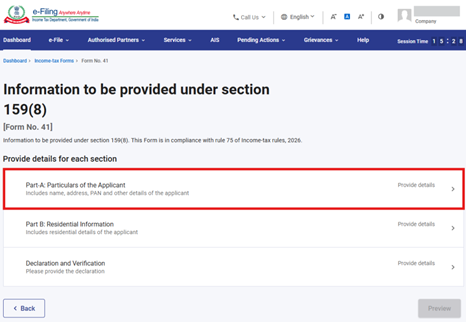
Official online screen example
Form 41 · Treaty information
The department’s manual shows the online form for prescribed information supporting a non-resident’s treaty-relief claim under section 159 and Rule 75.
What you will see on the form
Part A: applicant particulars · Part B: residential information · Declaration and verification
This is a screenshot from the official manual, not a blank paper form or proof of eligibility. Confirm the tax year and applicable Act with your CA. Filing is online through the official e-Filing portal.
Income Tax Department · Source checked 5 September 2026
Questions to take to an adviser
- Why does this precise asset fall under that treaty paragraph?
- Which anti-abuse and residence conditions have you checked?
- What must I report in both countries, and what if the claim is disputed?
Who can help
A CA experienced in the exact treaty and fund-unit case law, plus a qualified adviser in the residence country.
Check an adviser before paying or signingClaims, exceptions and the supporting evidence
Check what you may have heard
Source review: 5 September 2026 · Rules may change after this date.
UAE-resident NRIs pay no Indian capital-gains tax on mutual funds.
The treaty’s residual capital-gains clause can be relevant to qualifying fund-unit disposals. Entitlement depends on treaty residence, asset classification, applicable amendments and anti-abuse rules. The protocol alone does not settle every mutual-fund case or guarantee a refund.
A 2024 Mumbai ITAT decision confirms the advertised exemption.
The screenshots do not identify a case name, appeal number or order. That exact bench/year assertion could not be verified against an official order. It is not used here as precedent; ask an adviser for the full order and its current appeal status.
The eleven listed countries all mean zero capital-gains tax.
Treaties differ, and allocation of taxing rights is separate from domestic tax in the residence country. Germany’s official guidance describes taxable investment gains. The list cannot be treated as a zero-tax eligibility chart.
Country-by-country claim check
Choose a country from the screenshot to see the evidence and the remaining question.
Selection stays in page memory. This is an evidence check, not a determination of residence or exemption.
Sources & review limits
Published by NRIdisha. Prepared with AI assistance. No individual author or qualified professional reviewer is credited for this guide.
Official sources support the statements they address. They do not certify this guide or your eligibility. Open the source and check current amendments before acting.
Income Tax Department (opens in a new tab) · Reserve Bank of India (opens in a new tab) · National Portal of India (opens in a new tab)
Notification 282/2007: UAE individual treaty residence and the amended capital-gains article. Read with the treaty and subsequent applicable instruments.
Select the exact country and review its treaty, protocols and applicable MLI provisions.
Current 2025 Act form for non-resident treaty particulars under Section 159 and Rule 75; choose the applicable tax year.
Qualifying personal investment income is outside business activities for this corporate-tax test. Business facts can change the treatment.
Singapore generally does not tax personal investment gains; this does not resolve India’s treaty rights or trading-income cases.
Germany taxes categories of investment income and gains. A treaty allocation does not establish worldwide zero tax.
Keep this page’s title, the exact statement and the official source. Email them to support@nridisha.com. Do not include personal documents.