
In brief
Rental-income withholding and your final income-tax computation are different. Do not use a resident-landlord rule without checking whether it applies to your status.
Start with Income Tax Department: TDS on rent: resident and non-resident payees (opens in a new tab)
Keep citizenship, tax residence and FEMA residence separate
These labels answer different questions. Your nationality or OCI card does not alone determine the year’s Indian tax treatment. Establish the relevant year, travel history, income sources and exceptions.
Your next steps
0 of 5 steps complete · Next: Map each rental
Map each rental
Next stepList gross rent, vacancies, co-ownership, municipal payments and the loan details for every property.
Make your status clear to the tenant
Ask your CA for the applicable withholding process in writing so the tenant can comply.
Reconcile the evidence
Compare tenant payments, deduction certificates and the records available in your tax account.
Review permitted deductions
Ask for the actual computation and supporting conditions rather than accepting a tax percentage applied to bank credits.
Keep overseas reporting separate
Indian filing does not by itself settle reporting or foreign-tax-credit obligations where you live.
Suggested preparation sequence. Your authority may require a different order. Progress stays on this device.
What to have ready
0 of 4 preparedKeep documents in your own secure records. Tick what you have; nothing is uploaded.
Model the decision with your own figures
Prepare the dates, currencies, costs and amounts you know. Keep tax eligibility, provider access and uncertain assumptions on your adviser’s question list. The calculators show those assumptions explicitly.
For a return to India, add education, parents’ support, healthcare, partner income and locked funds to the household timeline. Bring supporting-tool figures into it only after reviewing timing, currency and overlap.
Recognise the official form
Preview before you visit the official portal. Do not enter or upload personal information here.
 Enlarge preview ↗
Official online screen example
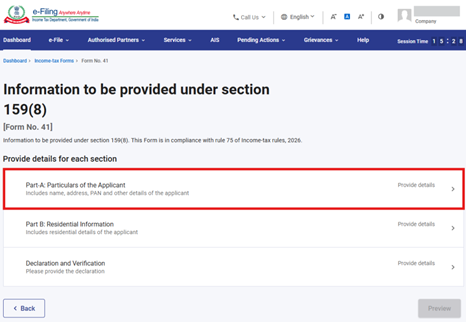
Form 41 · Treaty information
The department’s manual shows the online form for prescribed information supporting a non-resident’s treaty-relief claim under section 159 and Rule 75.
What you will see on the form
Part A: applicant particulars · Part B: residential information · Declaration and verification
This is a screenshot from the official manual, not a blank paper form or proof of eligibility. Confirm the tax year and applicable Act with your CA. Filing is online through the official e-Filing portal.
Income Tax Department · Source checked 5 September 2026
Questions to take to an adviser
- Has the tenant used the correct non-resident withholding process?
- Which deductions apply to this property and tax regime?
- How will excess withholding or missing credits be handled?
Who can help
A CA familiar with NRI rental income; an overseas adviser if required in your country.
Check an adviser before paying or signingSources & review limits
Published by NRIdisha. Prepared with AI assistance. No individual author or qualified professional reviewer is credited for this guide.
Official sources support the statements they address. They do not certify this guide or your eligibility. Open the source and check current amendments before acting.
Income Tax Department (opens in a new tab) · Reserve Bank of India (opens in a new tab) · National Portal of India (opens in a new tab)
Explains the distinction under the 1961 Act. Use tax-year-specific guidance for current filings.
Return guidance for AY 2026–27. Check the period before using its section references.
Current filing forms, notices, tax records and taxpayer guidance.
Keep this page’s title, the exact statement and the official source. Email them to support@nridisha.com. Do not include personal documents.